
You will see two different economies in this week’s data. Retail sales missed across the board in July, though part of that drop is payback from promotional events like Prime Day landing in June. The University of Michigan sentiment index fell well short of expectations, and the split by income was wide: the bottom third dropped to about 40 while the top third rose above 60. Meanwhile, the New York and Philadelphia Fed manufacturing indexes climbed to their highest levels since 2021, and the Philly Fed’s six-month outlook posted the largest one-month jump in the survey’s history. The Atlanta Fed’s GDPNow model is tracking third-quarter growth at 4%. Here are the data.
US Economy
Retail sales unexpectedly dropped in July and missed consensus estimates across the board. The key “control group”—a direct input for GDP—fell at the fastest pace since January 2025. Promotional sales events such as Amazon Prime Day occurred earlier this year, in June, pulling forward sales. The drop in July is largely a payback from those events, dragging down nonstore sales.
The University of Michigan consumer sentiment index deteriorated sharply, undershooting market expectations. The report noted that “large reductions were seen among older consumers, lower-income consumers, and those without a college degree,” who are “particularly vulnerable to any erosion of purchasing power stemming from inflation.” The decline was broad-based across the current conditions component and the expectations component.
The Atlanta Fed’s GDPNow model is now tracking Q3 GDP at 4%, down from 4.3% on August 14.
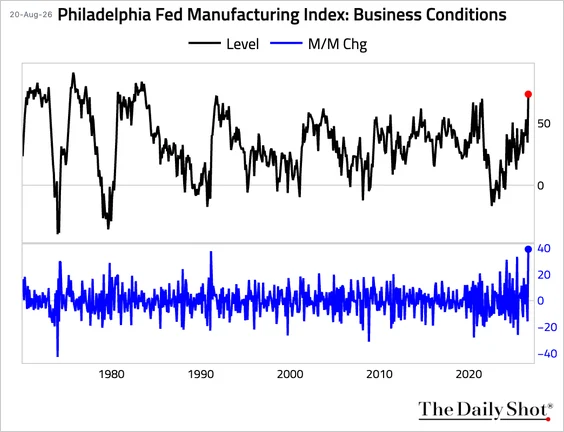
The New York Fed’s Empire State Manufacturing Index climbed to the highest level since December 2021. The Philadelphia Fed’s manufacturing index surged to the highest level since April 2021, defying expectations for a decline. The six-month-ahead business conditions indicator posted the largest one-month increase in the survey’s history to reach the highest level since August 1983.
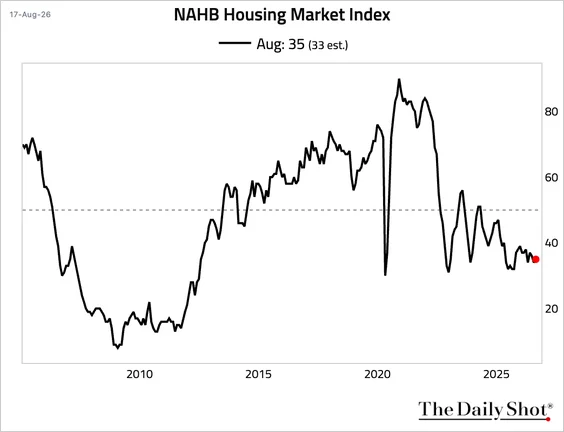
The NAHB homebuilder sentiment index rose by just one point.
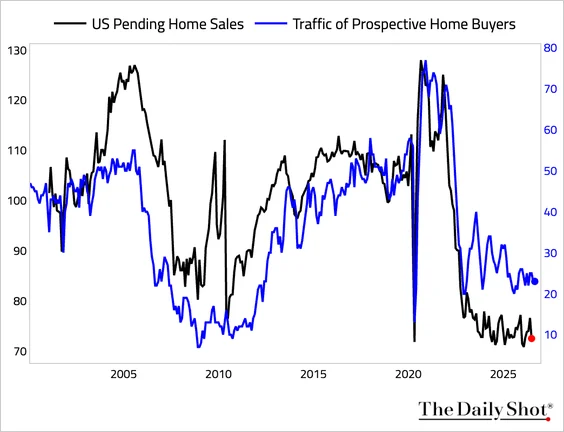
The overall level of housing activity remained subdued. Both the home value and observed rent growth picked up year over year, according to Zillow.
Consumer sentiment diverged sharply by income, with the bottom third falling to about 40 while the top third rose above 60, underscoring greater pressure on lower-income households from elevated gasoline costs. Prescription drug prices registered the steepest year-over-year decline in six decades.
What are Americans’ top aspirations?
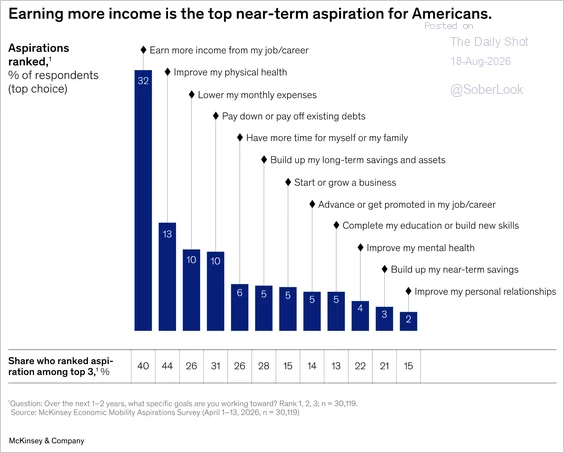
Source: McKinsey Read full article
These are the factors that impede making progress toward aspirations.
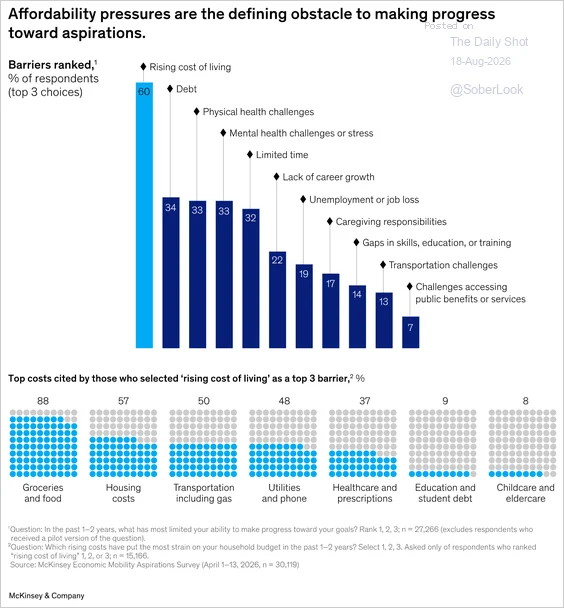
Source: McKinsey Read full article
Industrial production posted modest gains for a second consecutive month. Both manufacturing and utilities output rose.
Production of consumer goods remained in contraction, but capex-sensitive business equipment output has been strong.
AI-driven computer and electronics production continues to surge, accounting for roughly half of overall manufacturing output growth, while nearly all remaining gains are concentrated in aerospace and other advanced industries. In contrast, lower-value-added manufacturing has stagnated. Capacity utilization inched up.
Housing starts tumbled more than expected, with single-family starts slumping to the lowest level since November 2022. Building permits rebounded firmly, signaling a potential stabilization in residential construction ahead. Pending home sales fell in July to their joint-second-lowest level on record as higher mortgage rates, weakening consumer confidence, and softer hiring weighed on demand.
Import and export prices both declined. Airfares—the source data for the foreign travel component of core PCE—fell month over month. Import prices for computer peripherals and parts point to further upward pressure on core PCE inflation from electronics prices this year.
US national debt has surpassed $40 trillion and exceeds GDP by 20%. The vast majority of the government’s spending goes to programs that promise benefits to individuals, such as Social Security and Medicare. Total federal debt per person is approaching $120,000.
Initial jobless claims fell to 206,000, below consensus and signaling limited layoffs. Continuing claims edged up but are still lower than the same period last year.
US employer health-insurance expenses are projected to increase 11.1% in 2027—the steepest gain in more than two decades.
US Stock Market
More than 75% of S&P 500 constituents closed above their 200-day moving averages last Thursday for the first time in more than three and a half years, underscoring broader participation in a bull market. Breadth is also broadening for global equities.
Bank of America’s survey shows that global fund managers are very bullish. US company earnings are running well above trend.
The US is capturing a larger share of global profits.
Analysts expect hyperscaler EBITDA margins to rise to roughly 50% by decade-end from about 30% in recent years, a critical assumption underpinning the economics of massive AI capital spending.
The Fed
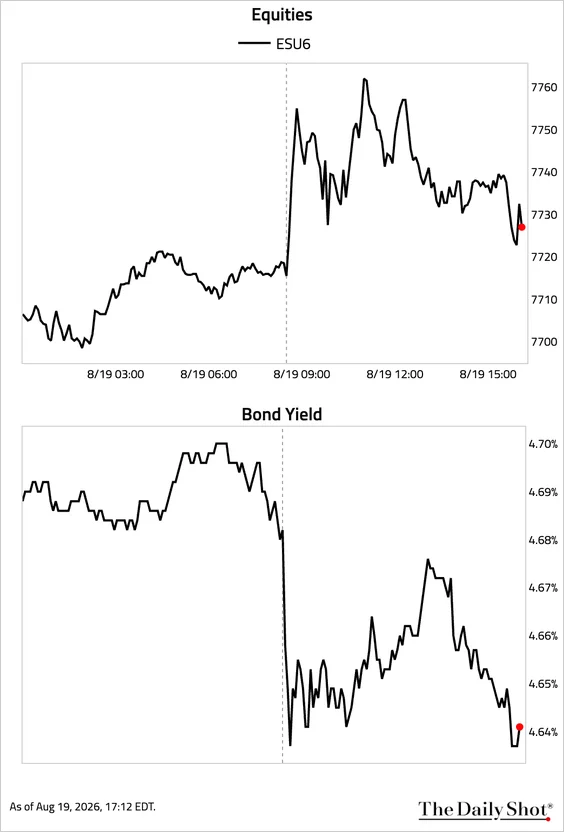
The Treasury will at least double buybacks of 10- to 30-year nominal bonds to $4 billion per operation from September 9 to November 4 (roughly $16 billion of additional purchases per quarter), while leaving coupon auction sizes likely unchanged, effectively financing the additional purchases through increased bill issuance. Here’s a look at the intraday market reactions. The long end of the Treasury curve rallied. Front-end yields initially rose but ended the day slightly lower. J.P. Morgan warns that the expanded bond buybacks may provide only fleeting relief to long-term yields and could erode market credibility, raising term premiums unless accompanied by meaningful fiscal consolidation.
While the maneuver initially knocked the 30-year yield (US30Y) down 10 basis points to 5.19%, the relief was short-lived as yields quickly resumed their climb back to 5.26% during trading on Thursday.
The 10-year Treasury yield is around 4.7%, right where it began yesterday and close to where it has been for the past month.
It’s just about the same with the 30-year yield. It’s trading around 5.2% as we write, only slightly below yesterday’s highs and still within a general uptrend of the summer.
Clearly, the plan hasn’t “worked” as Bessent thought. On CNBC today, he floated the idea of doubling down and buying back even more debt.
The Treasury Department is going to “make a market” for long-term U.S. debt, Bessent said in the television interview.
Did he really just say that?
If the U.S. Treasury has to “make a market” for American debt, that means there isn’t one already. Sadly, that’s no surprise… with the pace of inflation north of 3%, U.S. debt growing past $40 trillion, foreign buyers open to alternatives, and no end of any of it in sight.
Bessent put his best spin on it.
“There’s nothing magic about the 40 trillion number, and we can grow our way out of that,” he said. “Our message to our allies, our trading partners, is that global growth is the way to take care of this mountain of debt.”
He also said that two years ago, when the U.S. debt was “only” at $35 trillion.
The bond market looked right through it. Mr. (Stock) Market often overreacts in knee-jerk ways to news and developments. But Mr. (Bond) Market is typically ahead of the game at sniffing out what’s really going on with the economy and markets… and the risks ahead.
Federal Reserve policy – expected and real – matters, too.
Under new Chair Kevin Warsh, the Fed has kept its benchmark bank lending rate steady. Warsh hasn’t raised the federal-funds rate even as inflation numbers are elevated above the central bank’s supposed 2% goal and longer-term yields were moving higher as the Fed met last month.
Even if Warsh wanted to raise rates, he’s going to face pressure against it and perhaps even do the opposite. As we wrote just on Tuesday, Trump hasn’t publicly called for lower rates from his new Fed chair yet. But he could be getting there.
Yesterday, while saying that Warsh is doing a “great job,” Trump also said interest rates are “artificially high” and lamented the political nature of the Fed board and those who voted for higher rates at the central bank’s previous meeting.
Great Quotes
“There’s no such thing as a free lunch.” – Milton Friedman
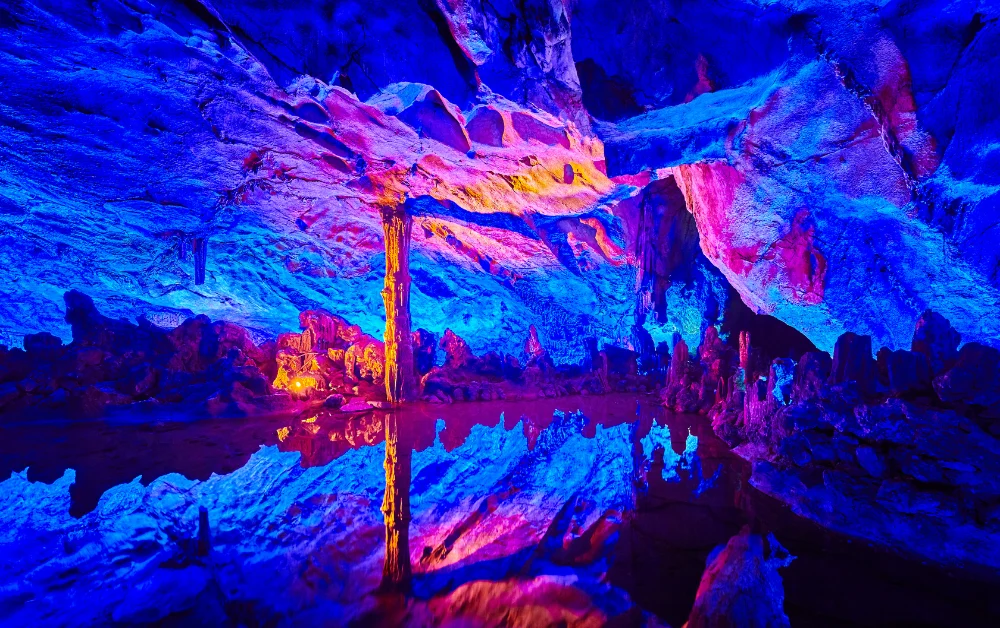
Picture of the Week
Reed Flute Cave, Guangxi, China
All content is the opinion of Brian Decker